Storm and emergency
Storm damage roof replacement in Dallas
When a storm damages most of a roof, the job becomes a claim: documentation, an adjuster, a scope, often a supplement, and only then a replacement. We handle the roofing side of all of it.
- We answer 24/7
- Dallas service office
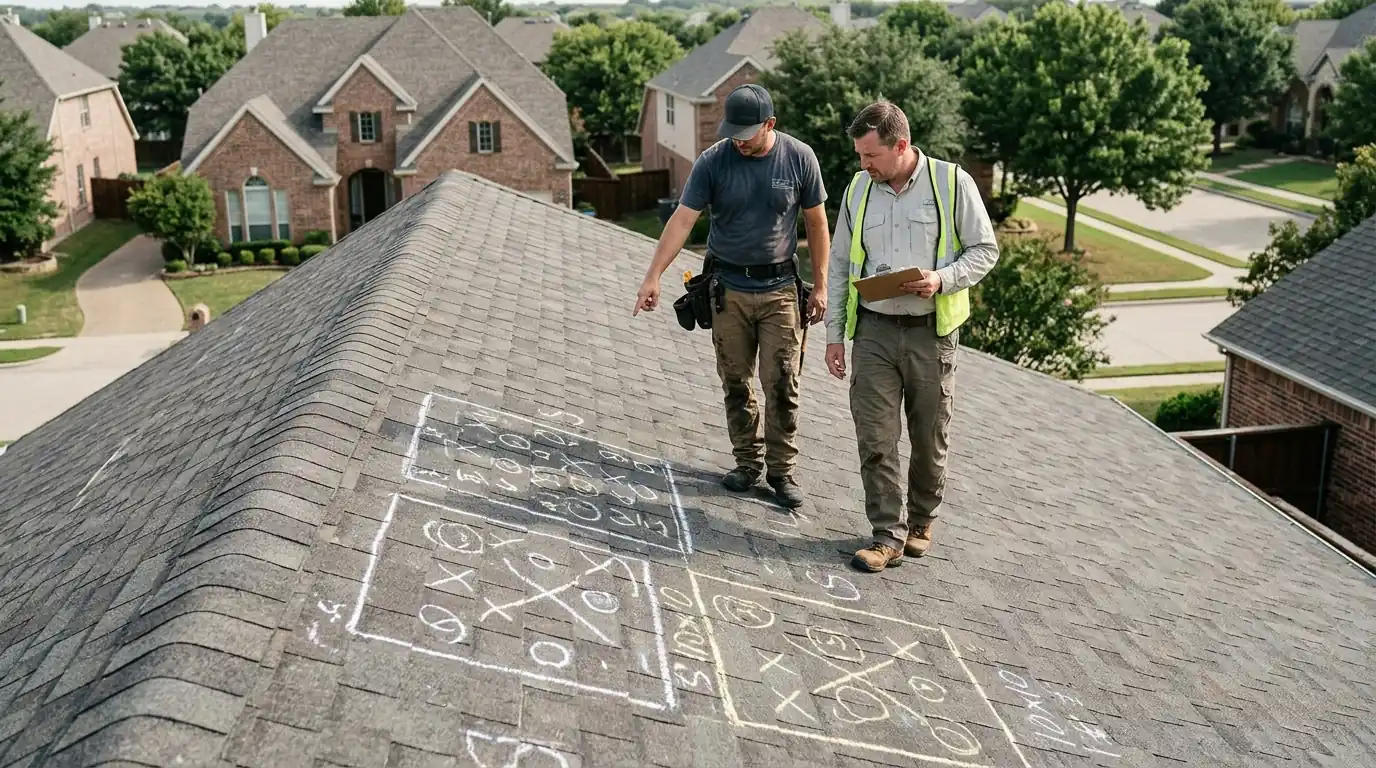
- Adjuster met on the roof
- 24/7Calls answered
- DallasService office
- EnnisHead office
- 1 to 2Days, most re-roofs
Quick answer
Storm damage roof replacement in Dallas runs through the insurance claim: we inspect and photograph every slope, you file the claim, we meet the adjuster on the roof, compare the carrier's scope to ours, submit supplements for anything missed, and replace the roof once funding is agreed. Texas deductibles are usually a percentage of dwelling coverage, and waiving them is illegal.
The job
How a storm replacement differs from a planned one
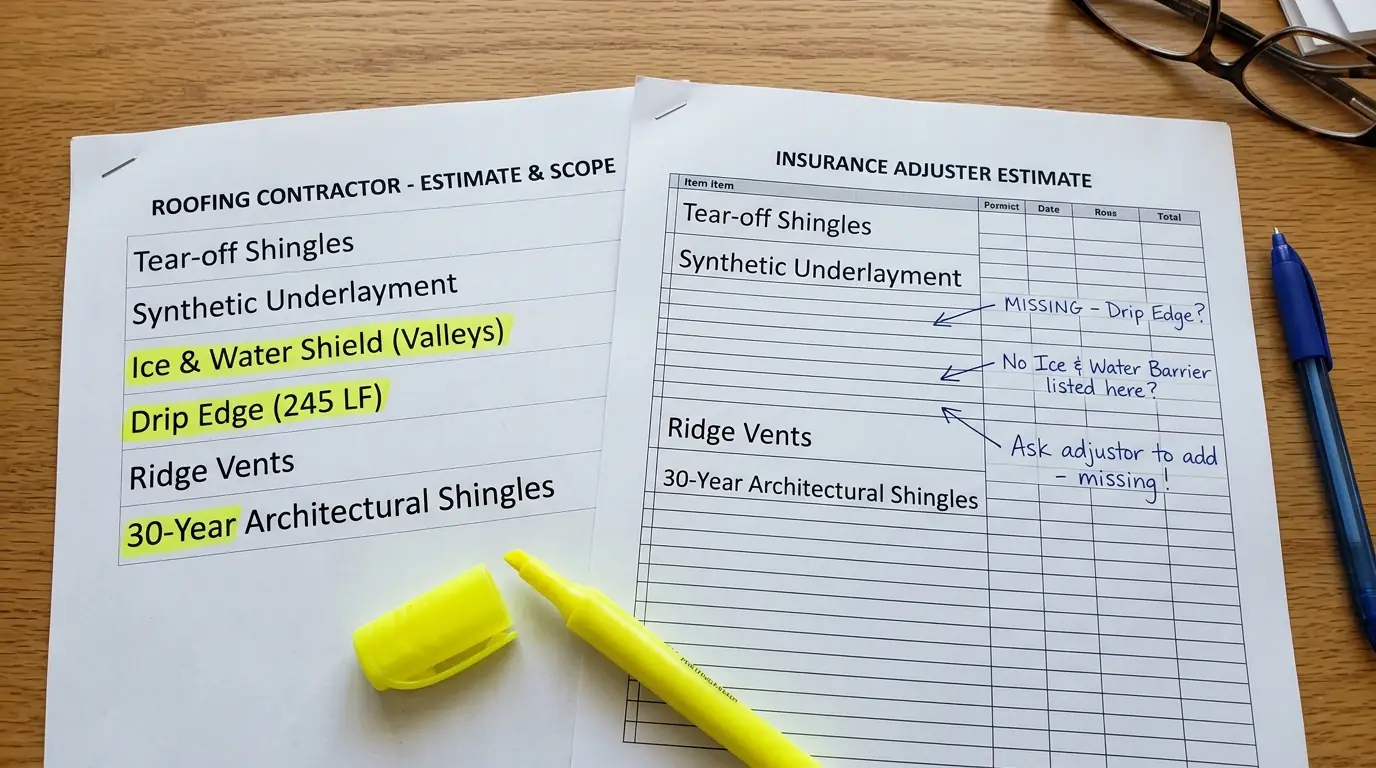
The roofing is the same: full tear-off, new underlayment, flashing, vents and shingles. What changes is who decides the scope. The carrier's adjuster writes an estimate, and it is common for that first estimate to miss items like drip edge, code-required ice and water shield, or the steep-pitch charge.
Our job before the tear-off is making the documentation complete enough that the scope matches the roof. You stay the policyholder and make every decision about the claim.
Updated September 2026
Warning signs
Signs the storm damage is a replacement, not a repair
Hits across every slope
Not one side; the whole roof took it.
A quarter of a slope damaged
Carriers often replace the whole slope.
Discontinued shingle color
Repairs cannot match, so slopes get replaced.
Brittle older shingles
They break when lifted for repair.
Wind and hail together
Creased tabs plus bruises on the same roof.
Interior leaks after the storm
Water already through the underlayment.
Dented vents on every slope
Collateral damage confirming the extent.
What happens after you call
From the storm to the finished roof
Inspection
Every slope photographed; hits counted in test squares.
You file the claim
With our report attached.
Adjuster meeting
We walk the roof with the adjuster.
Scope comparison
Carrier's estimate checked line by line against ours.
Supplements
Missed items submitted with photos.
Replacement
Permit, tear-off and new roof in one or two days.
Completion paperwork
Invoice and photos sent so you can recover depreciation.
Timeline
How long a storm replacement takes
The inspection is an hour and the adjuster visit is usually within a couple of weeks of filing. After a metro-wide storm, both stretch. Once the scope is agreed, the permit takes a few business days and the roof itself one or two days.
Insurance claim walkthrough
You call your carrier and open the claim; we supply the inspection report with a slope diagram, hit counts and photos of every damaged component. When the carrier's estimate arrives we go through it line by line against our scope and show you, in writing, where they differ. We do not negotiate your settlement or act as your adjuster, which Texas law does not allow a contractor to do, but we make sure the roofing facts are on paper. The report is yours either way.
Adjuster meeting and scope
Being on the roof when the adjuster is there matters more than anything else in the process. We walk them to every test square, point out the dented vents and split boots, and answer questions about materials and code items as they write. Most scope disagreements get settled right there, on the roof, instead of by email three weeks later. We bring the ladders and harnesses so the inspection is not rushed. Anything left open is written down with the adjuster's name and the date.
Supplements and depreciation
A supplement is a documented request for items the first estimate left out: drip edge, starter course, ice and water shield, extra decking found at tear-off, or permit fees. We file them with photos. On a replacement-cost policy, the carrier holds back depreciation until the work is finished; we send the completion paperwork so you can recover it. On an actual-cash-value policy, depreciation is not recovered, which is worth knowing before the storm. We check which one you have before the tear-off starts.
Full tear-off after a storm
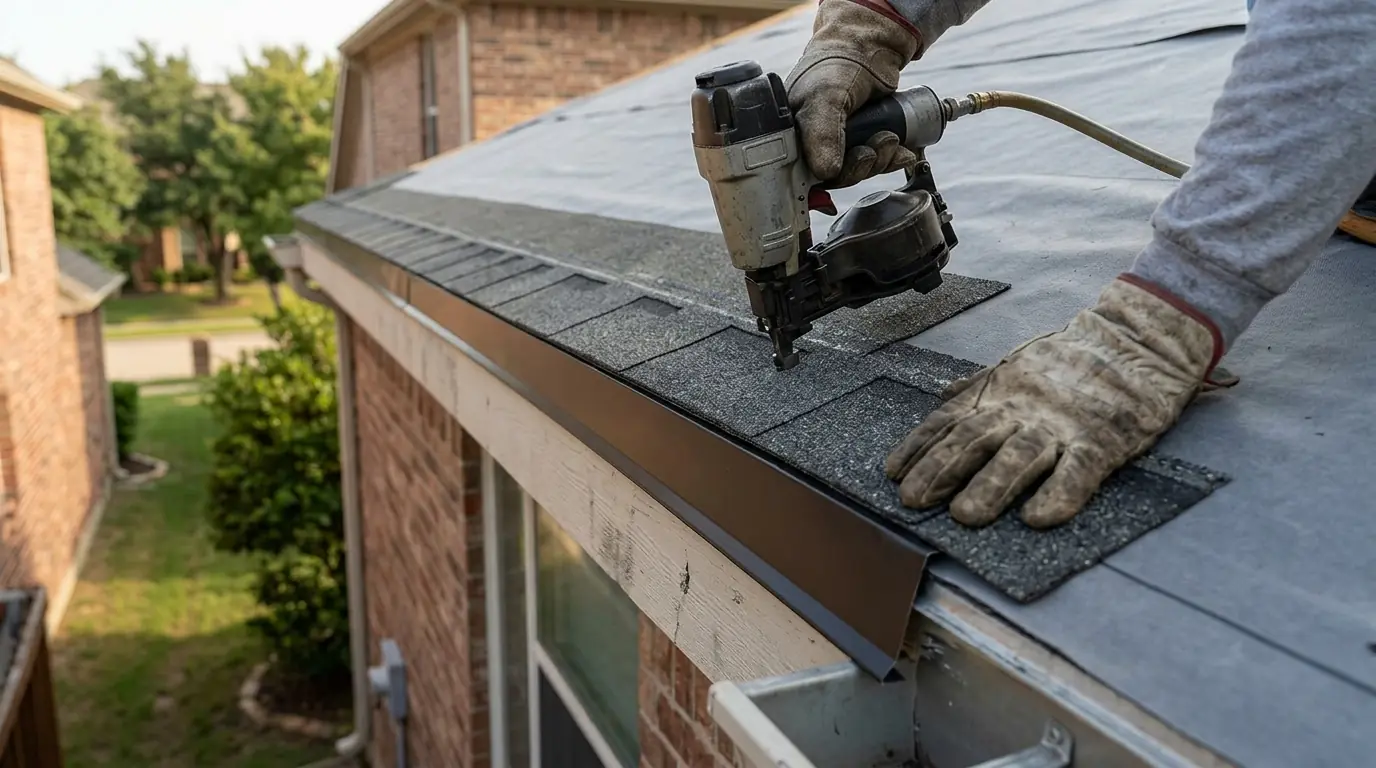
Once the scope is agreed, the replacement is scheduled like any other: permit pulled, materials delivered, tarps over landscaping, tear-off to the deck, and the new roof in one or two days. Many homeowners use the claim to upgrade to Class 4 shingles from GAF, Owens Corning or CertainTeed, paying only the difference, because the next spring storm is coming either way and many Texas insurers discount premiums for them. Every item on the agreed scope is installed and photographed, because the completion photos are what your carrier checks before it releases the held-back depreciation.
Roofing in Dallas
What we see on Dallas roofs
On older roofs, Texas insurers that still cover storm damage often shift payouts to actual cash value, so depreciation comes out of what you receive, and some carriers cap coverage by roof age. Carriers also commonly treat damage on a quarter or more of one slope as grounds to replace the whole slope. On a Dallas claim the process from inspection to finished roof typically runs three to four weeks, with the installation itself taking one or two days.
Budget
What a storm replacement costs you
On a covered claim your cost is mostly the deductible, plus any upgrades you choose.
The Texas deductible on these claims is typically 1-2% of dwelling coverage in Texas. That is a planning range from published Dallas market data, not a quote, and your roof size, pitch, layers and decking condition move it either way.
- Deductible
Set by your policy; always paid by you, never waived.
- Policy type
Replacement cost recovers depreciation; actual cash value does not.
- Roof age
Older roofs are more likely to be paid at actual cash value.
- Upgrades
Class 4 shingles or better underlayment at the difference in cost.
- Supplements
Missed code items added to the carrier's scope.
- Decking found at tear-off
Documented and submitted as a supplement.
- Non-storm items
Anything not caused by the storm is priced separately.
Brands we install and service
Questions we get
Storm replacement questions
Either; calling us first means the claim starts with a documented roof.
No. It is illegal in Texas, and any roofer offering it is a warning sign.
We give you the photos and counts for a re-inspection request.
A documented request to add items the first estimate missed.
On replacement cost, after completion paperwork; not on actual cash value.
Yes, paying the difference, and it often lowers your premium.
Typically three to four weeks from inspection to finished roof.
No. In Texas you choose your contractor.
Storm hit your roof? Start with the documentation
A report with every slope photographed is the strongest start a claim can have.